
Operational review
OVER THE COUNTER (OTC)

WERNER VAN RENSBURG
Managing Director
NATALIE ZAROUDOUKAS
Financial Director
Turnover
R1 989m
(2017: R1 849m)
Top 10 brands
turnover
R1 131m
Trading profit
R400m
(2017: R342m)
Sales


MARKET SHARE
-
Volume market position(1) #1
-
Volume market position(1) #1
-
Value market share(1) 21.6%
-
Volume market share(1) 34.8%
-
Script share(2) 36.00%
-
(1) IQVIA MAT Jun 2018 S1 and S2 (2) Impact Rx Jun 2018 constructed (categories in which we compete)
NUMBER OF EMPLOYEES
-
433 factory and laboratory
-
160 sales, marketing and administration
TOP BRANDS
Adco-Dol
Allergex
Corenza C
Citro Soda
Alcophyllex
Adco-Napamol
Betapyn
Solphyllex
Dilinct
Mypaid
MANUFACTURING
Capacity per annum
-
28 million effervescent tablets
-
400 tonnes Effervescent granules and powders
-
12 million ℓ
Oral liquids -
Accreditations
South Africa (SAHPRA), Ghana (FDB), Malawi (PMPB), Kenya (PPB), Zimbabwe (MCAZ), and Ethiopia (FMHACA). -
Location
Clayville
OVERVIEW
OTC supplies medication for patients in South Africa's private and public sector as well as to certain export markets, competing in the self-medication category (Schedule 1 (S1) and 2 (S2)) in Pharmacy, and also in the FMCG channel (Schedule 0 and unscheduled) with an aggregated complement of 103 premium and economy brands.
The division's brand portfolio and operational excellence have assisted in maintaining its volume and value leadership position in Schedule 1 and Schedule 2 in pharmacy. Two in every five packs, S1and S2 products, sold in the private sector, is an Adcock Ingram product.
The division competes primarily in the following therapeutic categories:
PERFORMANCE
|
|
|
|
|
|||||||||||||||||||||||
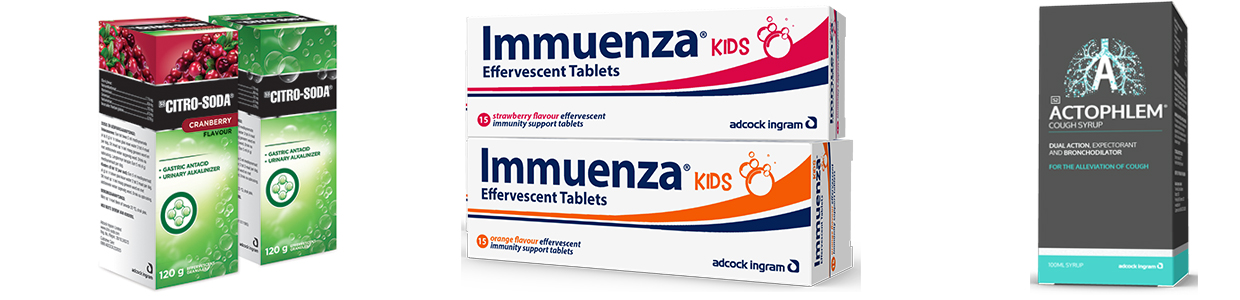
| The OTC division is the market leader in the pain category in pharmacy, with its top ranked brand Adco-Dol continuing to outperform the market. The pain market has evolved significantly in the last year with the downscheduling of several brands from schedule 3 (prescription only) to schedule S2 (OTC). The division offers a full breadth of economy and premium brands with Adco- Napamol performing particularly well in the economy sector. | Despite difficult economic conditions, core brands like Corenza, Solphyllex and Alcophyllex contributed to sustained growth in this mature and highly competitive category. OTC remains a leading player in this market, with representation across cold preparations, expectorants and cough sedatives. The division prioritises innovation and recently launched its new immune booster Immuenza, as well as a packaging upgrade for Actophlem, and the repositioning of Stearns to earn the trust of a diverse customer base. | OTC is a significant participant in this market through one of its flagship brands Allergex and Allergex Non-Drowsy. The anti-histamine portfolio has had several exciting new launches in the last few years and now has full representation across several key molecules. The extended portfolio of brands includes Levogex (levocetirizine), Ceticit (cetirizine) and Adco- Desloratidine (desloratidine). | The heartburn and indigestion category is very relevant to Adcock Ingram with high efficacy brands such Citro-Soda and Adco Mayogel trusted by healthcare practitioners and consumers, both performing strongly in pharmacy and FMCG. Citro-Soda is supported by extensive above-the-line campaigns, digital promotions and in-store activations. | The energy category in
both pharmacy and FMCG
is under pressure given the
discretionary nature of the
category. vita-thion as a
front shop brand relies on
innovation with exciting
new upgrades and line
extensions that were
launched during the year. * Pharmacy rank |


MARKET TRENDS
- Economic pressure on the consumer tends to shift mix towards more economy brands and/or smaller pack sizes.
- Recommendations by healthcare professionals are still highly valued.
- Rapidly advancing technology is changing the way patients access advice and execute transactions.
- Mobile penetration, in particular interactions on social media are playing a greater role in how people interact with brands.
- Consumers are actively involved in their own health and wellness, seeking to educate themselves on self-care and preventative therapies.
- Increased patient access to medicines through down-scheduling from Prescription to OTC of certain molecules.
- Convenience and access to medicines in specific channels, plays an important role in the consumer's choice.
- Consumer behaviour and consumption are influenced by factors such as loyalty programmes and retailer offerings.
STRATEGIC FOCUS
- Protect and build heritage brands.
- Enhance customer relationships through business partnering and service delivery excellence.
- Launch innovative new products into new and existing categories.
- Focus on consumer education in line with the self-care and preventative consumer trends.
- Embrace the opportunities offered by digital penetration.
- Growth through acquisitions and partnerships.
- Expand into export markets.
- Ensure regulatory compliance in a changing environment.
- Quality and cost effective, proudly South African manufacturing.
ACHIEVEMENTS IN 2018
- Agreement signed with Abbott to market, sell and distribute Brufen, Calmettes, Duphalac and Creon.
- Rebranded vita-thion – 'vita-thion fizzies' and 'vita-thion extra'.
- Installed a fully-automated powder sachet packing line at the Clayville manufacturing site.
- Progress on construction of an ophthalmic manufacturing plant at Clayville.
- Clayville manufacturing site certified as a National Key Point.
PRESCRIPTION

ADISHA SINGH
Financial Director
ASHLEY PEARCE
Managing Director
Turnover
R2 238m
(2017: R1 938m)
Top 10 brands
turnover
R803m
Trading profit
R239m
(2017: R208m)
Sales


MARKET SHARE (1)
-
Value market share 7.0%
-
Value market position #3
-
Volume market share 10.9%
-
Volume market position #2
-
ARV private market share 16.6%
-
(1) IQVIA MAT Jun 2018, including MNC partnerships
NUMBER OF EMPLOYEES
-
320 factory and laboratory
-
212 sales, marketing and administration
-
126 in Genop
TOP BRANDS
-
Trivenz
-
Genpayne
-
Adco-Zolpidem
-
Myprodol
-
Topzole
-
Synaleve
-
Estrofem
-
Urizone
-
Xylotox
MANUFACTURING
Capacity per annum
-
6 million ℓ
Oral liquids -
500 tonnes Creams/Ointments
-
2 billion Tablets and capsules
-
Accreditations
South Africa (SAHPRA), Ghana (FDB), Malawi (PMPB), Kenya (PPB), Zimbabwe (MCAZ), and Botswana (DRU). -
Location
Wadeville
OVERVIEW
The Prescription division is focused on building and offering a broad range of quality and affordable medicines in specific therapeutic areas for patients consulting healthcare professionals, generally where prescriptions are required. During the year the business acquired Genop, a specialised instrument, surgical and pharmaceutical products company focused on the ophthalmic, optometry, skincare, aesthetic and plastic surgery segments in Southern Africa, and which also owns and markets the well-known Epi-Max range.
The division manufactures products in South Africa and India, as well as sourcing products from a range of partner companies, primarily based in Europe.
The portfolios of products are grouped according to therapeutic areas in order to facilitate promotion to relevant medical specialists:
PERFORMANCE
|
|
|
|||||||||||||
The Pain portfolio is the market leader in prescription pain
The pain portfolio includes leading, well-known brands such as Myprodol, Synaleve, Mypaid Forte and Myprocam. In the coming year this division will expand its chronic pain offering by introducing two innovative, long-acting transdermal patches for the treatment of neuropathic pain. |
Women's Health recognises and celebrates the uniqueness of women. The portfolio includes treatments related to menopause, vaginal dryness, urinary tract infections (UTIs) and osteoporosis. Women's Healthcare is proud to provide quality treatment options to meet the needs of South African women through specific stages of their journey through life. We are passionate about empowering women through information about healthcare and personal matters, helping women make informed decisions about their health and the treatment options available. The hormone therapy portfolio which includes Adcock Ingram's as well as partner brands is the leader in its class as measured in IQVIA. |
Dermatology covers a wide spectrum of dermatological conditions, including acne, eczema, emollients for dry skin, and brands for skin infections and psoriasis. Whilst most of these conditions are not life threatening, they significantly affect the patient's quality of life. The portfolio is comprised of brands from mainly two partners, namely Leo Pharma and Roche Holding AG. The 2018 financial year saw the full integration of the former Astellas products Protopic, SBR, Locoid and Zineryt into the Adcock Ingram stable, after the global acquisition of these brands by Leo Pharma. The expanded Dermatology portfolio now offers healthcare professionals a broader armamentarium in treating dermatological conditions, and has successfully positioned Adcock Ingram as the 2nd largest prescription dermatology franchise in the country, including well-known brands such as Fucidin, Roaccutane, Dovobet, Protopic and SBR Lipocream. |
|||||||||||||
|
|
|
|||||||||||||
The CNS portfolio has established itself as a multinational partner of choice for CNS brands in the private and public sector, promoting and distributing key brands such as Cipramil, Cipralex, Fluanxol and Rivotril. This portfolio also includes well known Adcock Ingram brands such as Stresam and offers treatments covering a range of conditions, such as depression, anxiety, epilepsy, Alzheimer's and schizophrenia. |
Adcock Ingram's anti-retroviral (ARV) portfolio consists of a range of high quality, cost effective, first and second line treatment options for adults and children living with the Human Immunodeficiency Virus (HIV). Trivenz, which is Adcock Ingram's once daily, single tablet regimen for the treatment of HIV, is currently the Company's leading prescription brand, providing treatment to approximately 70,000 people in the private sector. The brand is currently the fastest growing prescription brand in the Top 10 pharmaceutical brands in SA, and is currently the second most dispensed anti-retroviral brand in the private sector prescription market. |
The Generics portfolio contributes approximately one-third towards the division's revenue and consists of products which span the major therapeutic areas such as CNS, cardiovascular and pain. This diverse portfolio consists of brands which treat both acute and chronic diseases and are predominantly found within the prescription medication space. |


BUSINESS FOCUS
- Remain the multinational partner of choice.
- Drive growth and market access within the generics portfolio.
- Enter into high value and specialty markets with biosimilars and novel pain products.
- Leading supplier of locally manufactured ARVs to the private and public sectors.
- Improve factory capacity utilisation.
- Introduce products and partnerships in new or additional therapeutic areas.
MARKET TRENDS
- Shift in disease burden from infectious diseases (such as HIV and TB) to chronic diseases (South African Generics Market Outlook 2017–2022).
- The ARV market faces significant pricing pressure from generic competition and funders.
- The growth of house brand strategies, driven by corporate pharmacy groups, limits market penetration of generics.
- Increased interest in biosimilars.
- Pricing pressures, driven by funders, continue to shape the private market, by driving a switch to generics.
ACHIEVEMENTS IN 2018
- The acquisition of Genop in the second half of the financial year.
- The division continued to build on the strategy of being the multinational partner of choice with the on-boarding of Aclasta from Novartis in 2018.
- The acquisition of a first to market Arcoxia (Etoricoxib) generic from Specpharm.
- Down-scheduling of Genpayne and Fucidin to Schedule 2, now available over the counter without a prescription.
- Trivenz, for the treatment of HIV, reached R200 million in sales and is cited as the fastest growing brand in the Top 10 pharma brands (SAHCI, May 2018).
- Completion of phase two of the upgrade of the liquids, creams and ointments facility in Wadeville.
HOSPITAL

COLIN SHEEN
Managing Director
MOHAMED MANGEL
Financial Director
Turnover
R1 348m
(2017: R1 257m)
Trading profit
R95m
(2017: R58m)
Sales


MANUFACTURING
Capacity per annum
-
33 million
large volume parenterals -
35 million
small volume parenterals -
4 million
pour bottles -
1 million
Blood collection bags -
Accreditations
South Africa (SAHPRA), and Kenya (PPB) -
Location
Aeroton
-
Only medical grade LVP plastic manufacturer on the continent
-
Extrude >1 900 metric tons of PVC sheeting and tubing per annum
NUMBER OF EMPLOYEES
-
115 sales, marketing and administration
-
648 factory
OVERVIEW
Adcock Ingram Critical Care (AICC) is a leading manufacturer and supplier of hospital and critical care products in Southern Africa. Products are offered through multiple portfolios and across wide-ranging customer channels.
The business is a fully integrated operation which spans regulatory, manufacturing, marketing, sales and distribution. Beyond its world-class commercial capability, AICC manufactures an extensive range of products in its unique dual-process factory which comprises a comprehensive plastics extrusion plant together with a fully accredited pharmaceuticals manufacturing facility.
AICC is a progressive healthcare company with ever-evolving and broadening portfolios. At the core, AICC holds a solid market leadership position in intravenous solutions, renal therapies and blood transfusion therapies where it is the largest supplier of blood donation bags to the South African National Blood Services. Other product portfolios include small volume injectables, infusion systems, invasive diagnostics, nutrition, and specialised pharmaceuticals.
In its efforts to maintain its leadership position, AICC continues to expand into newer novel portfolios which include growth in opioid substitution therapy, oral and injectable analgesia, additional injectable pharmaceuticals, immunosuppressants, hand and surface disinfectants and kinesiology tapes.
Renal
|
Medicine Delivery
|
Transfusion therapies
|
Specialised Pharmaceuticals
|

BUSINESS FOCUS
- Continue to concentrate its efforts on nurturing focussed portfolios with key attention on product mix, processes and people.
- Uncompromising attention to customer service in supply, delivery, service and communications.
- Maintain and grow its market leading position in both established as well as newly penetrated therapy areas.
- Expand into adjacent categories through licensing, partnerships and strategic alliances.
- Key focus on operations with emphasis on yield, reducing waste, efficiencies and automation.
- Maintain a close relationship with government and support national communities in providing quality healthcare products affordable to all.
- Maintain close relationships with all stakeholders to build trust, demonstrate commitment and deliver to expectation.
ACHIEVEMENTS IN 2018
AICC has progressed several innovations through the 2018 financial year which support growth ambitions in its base business, and aspirations in adjacent categories as it looks to expand its portfolio.
These include:
- Kinesiology – obtained licensing rights for a leading kinesiology tape "SpiderTechTM". This positions AICC in the 'home critical care' space where it will seek to bolt on product extensions.
- Disinfectants – AICC has launched its own range of hand and surface disinfectants. Housed under the Adco-Hygiene brand, AICC has made available several unique formulations which vary in size, fragrance, texture and colour. The range is accredited with standards authorities, such as NRCS (National Regulator for Compulsory Specifications), and has anti-bacterial, anti-viral and anti-fungal properties. The products are intended for home and professional use.
- In the Renal business, 2018 has seen the introduction of an innovative new cycler for PD which allows healthcare professionals to monitor dialysis patients remotely via a mobile app.
CONSUMER

GAIL SOLOMON
Managing Director
LAUREN SHIMMIN
Financial Director
Turnover
R687m
(2017: R689m)
Top 10 brands
turnover
R629m
Trading profit
R112m
(2017: R110m)
Sales


MARKET SHARE1
-
Analgesics
30% -
Feminine hygiene
49% -
Energy
supplements
41% -
Gut Health
27% -
Suncare
2%
NUMBER OF EMPLOYEES
-
68 sales, marketing and administration
TOP BRANDS
-
Panado
-
Bioplus
-
ProbiFlora
-
Compral
-
Gyna Guard
-
Cepacol
-
Gummy Vites
-
Viral Guard
-
Island Tribe
-
Freshen
SALES BY CUSTOMER
CHANNEL

1 Source: ACNielsen June 2018 – defined market comprises the category, customers and channels for the segments in which we compete
OVERVIEW
The division provides products through the independent wholesale, pharmaceutical wholesale, corporate pharmacy and retail channels. Brands fall into the following categories:
 |
 |
 |
 |
 |
 |
 |
 |
||||||||||||||
| Pain management Panado Compral |
Cough, colds and flu Cepacol L.C.C |
Personal care Gyna Guard Island Tribe |
Vitamins, Minerals and Supplements (VMS) Gummy Vites, Bestum, Natrodale, Viral Guard, Pro-Oxidin, Arthro Guard, ADDvance |
Nutrition Suganon Shape |
Energy Bioplus Regmakers |
Gut health ProbiFlora |
Laxatives Freshen |
PERFORMANCE
Analgesics The iconic Panado brand, which has been trusted by South Africans for decades, is the second biggest brand within the analgesics category in South Africa with a 22% market share. Panado continues to be supported with extensive marketing campaigns that defend the brand's equity and heritage. The rising star within the pain portfolio is Compral, which has grown at 14% this year, well ahead of the category growth. Compral launched the "I Don't Do Pain" campaign on various platforms during the year. |
Feminine hygiene Gyna Guard remains the market leader within this category with a market share of almost 50%, and growing ahead of the category growth. Gyna Guards' comprehensive range of products have been specially formulated by a Gynaecologist – to cleanse, relieve and take care of intimate areas, keeping women healthy and fresh. The brand's growth has been driven by extensive marketing campaigns on television and social media, focussing on awareness, education on general feminine health, as well as the new innovation of Gyna Guard Vaginal Capsules. |
Sun Care Our new brand, Island Tribe, boasts a comprehensive range of sprays, lotions and gels, and was supported with strong digital as well as instore marketing campaigns over the summer period. Island Tribe will continue to grow off a small base with the imminent launch of an exciting Kids range. |
Energy supplements Bioplus is the market leader within this category. The single dosage sachet continues to be the top seller in the range. On-thego product offerings lead consumption trends in energy, affirming the launch of the energy drink to be in the right direction for the brand. Extensive brand building investment has ensured that Bioplus remains the market leader and continues to create demand for the category and brand. |
Gut health ProbiFlora has a range of clinically proven probiotic strains formulated to normalise bowel flora and general intestinal health. ProbiFlora continues to perform well in the face of increased competition from house brands. |
MARKET TRENDS2
- South African retailers and manufacturers will continue to face a significant shift in the way consumers behave, mainly due to the economic conditions tightening, the drop in consumer confidence and online shopping on the increase.
- Consumers are focusing on deals within a store and increasing the range of stores they visit, consciously shopping for promotions.
- The average consumer has dropped three categories from their shopping basket and is spending less per store visit.
- Private labels are gaining share of the consumers' wallets.
- Branded retail outlets contribute 78% of the total basket followed by Independent retail outlets at 19%.
- Consumers of skin care products are seeking additional functions and benefits when purchasing skin care, with sun protection being one such benefit.
CONSUMER TRENDS3
Energy
Consumers are looking for more convenient and/or healthier product offerings.
Consumers have become more price and promotion sensitive.
Consumers are more format loyal (for example, an effervescent user will rather switch to another effervescent brand than a syrup of the same brand).
Feminine Hygiene
Consumers are seeking more information about their feminine hygiene.
Consumers have removed the "taboo" element. They are free to talk about feminine hygiene with their family and friends.
Pain
Consumers remain very loyal to specific formats, with limited influence to switch to another format at the point of purchase.
Personal Care
Beauty and personal care are showing resilience in a challenging economic environment despite consumers reducing their expenditure on non-essential items.
Economy brands are experiencing increased demand due to cost-conscious consumers.
Sun care
Increasing awareness among target audience and sophistication of consumer as they are now more "sun-smart".
Sun care faces growing competition from Skin care brands containing higher SPF.
Premium Sun care brands are declining in popularity as consumers trade down.
BUSINESS FOCUS
- Protect and grow the core business through investment in innovation and marketing.
- Entry into new categories of less regulated products via acquisitions and innovation.
- Expanding markets via exports.
- Improve access and availability of product to the consumer.
REVIEW OF 2018
- New leadership has been appointed in the last quarter of the financial year.
- A review of the business was done and certain structural and operational changes will be implemented.
- The business is focusing its efforts on
processes, people, customers, products and financial performance in the coming financial year.