
DORETTE
NEETHLING
Chief Financial Officer
Financial review
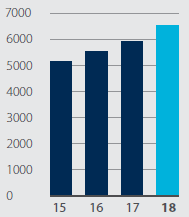
"We are very satisfied with this set of financial results which shows growth in turnover, trading profit and headline earnings from continuing operations for the fourth year in a row."
|
 |

|

|

|
|
Non-trading expenses of R47 million include:
- share-based expenses of R34 million;
- an impairment of the long-term receivable relating to the Tiger Brands Black Managers Trust of R3 million;
- a partial impairment of a Consumer intangible asset of just under R3 million; and
- corporate activity costs of R7 million.
The net finance cost for the year is R8 million, compared to net finance cost in the prior year of approximately R23 million. This reflects the lower debt following the early settlement of the Nedbank long-term loan as well as the improved average net cash position of the business.
Dividend income from the Tiger Brands Black Managers Trust is R4 million compared to R6 million in the prior year.
Equity-accounted earnings are R79 million, 24% ahead of the prior year and include National Renal Care, our joint venture with Netcare, our joint venture plant in India with Meiji of Japan, as well as our 25.1% shareholding in Ayrton Drug Manufacturing in Ghana.
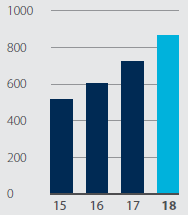
Profit before tax of R895 million, is 24% ahead of the prior year (R725 million).
The effective tax rate, adjusted for equity accounted earnings is 31%, with non-deductible expenditure causing the increase over the statutory rate.
The profit after tax for the year is R644 million compared to a profit of R520 million in 2017.
Discontinued operations reflect the sales of the India and Ghana businesses which were concluded in the first six months of the prior year.
Minorities in Novartis Ophthalmics and Menarini amount to R6 million.
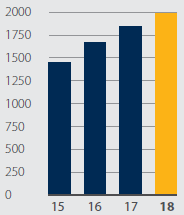
 OVER THE COUNTER (OTC)Turnover, just short of R2 billion is R140 million or 8% ahead of last year mostly arising from a 7% average price increase (driven by the non-regulated portfolio and exports) and the balance from mix with the introduction of the Abbott brands (Creon, Calmettes, Brufen, Duphalac) as well as the new product launches (Immuenza, Asic and GAP). |
|
|||||||

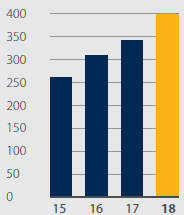
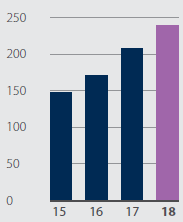
 PRESCRIPTIONThis division's turnover of R2.2 billion improved by 16%, with Genop contributing R224 million. An average price increase of 2% was realised and is reflective of the pricing pressure in parts of the generic and ARV portfolios. Volumes increased by just under 4% driven by the demand in the ARV private market. Mix, although impacted by the loss of a low-margin multinational partner contract, improved by 10%, substantially aided by the acquisition of Genop, and the on-boarding of the Astellas portfolio from Leo Pharma and Topzole from Takeda. |
|
|||||||


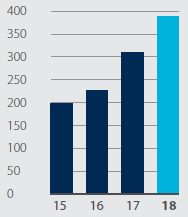
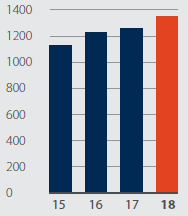
 HOSPITALTurnover of R1 348 million increased by 7% over the prior year, driven by volume improvement of 3%, a mix benefit of 2% due to the inclusion of the Pharma-Q range and an average price increase of 2%. The gross margin ended higher than the prior year benefitting from the positive exchange rate impact on imported inventory and an improved sales mix with more sales into the private mark. |
|
|||||||

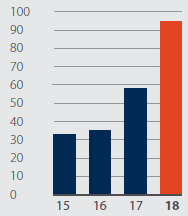
 CONSUMERTurnover of R687 million declined by 0.3% over last year, impacted by a decline in volumes due to the difficult trading conditions as a result of the continued pressure on the average consumer's disposal income. This was partially mitigated by an average realised price increase of 2% and a full year's inclusion of the Island Tribe sunscreen range launched at the end of the prior financial year. |
|
|||||||


|
BALANCE SHEET
NON-CURRENT ASSETS
Intangible assets, including goodwill, have a carrying value of R626 million and comprise of Generic, Consumer and OTC trademarks and licence agreements. Intangibles of R285 million (R164 million goodwill; R121 million other intangibles) were recognised on the acquisition of Genop. Other financial assets of R34 million are primarily the capital contribution made to the Tiger Brands Black Managers Trust which has reduced as options were exercised since June 2017.
CURRENT ASSETS
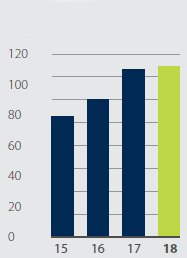
Inventory of R1.6 billion (2017: R1.2 billion) is stated at the lower of cost and net realisable value. Days in inventory are 136 days compared to 115 days at June 2017. The increase results from the acquisition of Genop, the take-on of new product portfolios including Astellas, Takeda, Pharma-Q and Abbott, and a planned increase in raw materials for the production of Trivenz.
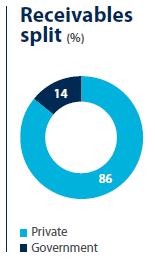
Days in receivables are 65 days, an excellent improvement on the 70 days reported in June 2017. The book remains wellcontrolled and 91% of receivables are due within 60 days or less.
The state is currently complying with an agreed payment plan, which allows for the settlement of arrears over two years.
BORROWINGS
Both long-term and short-term borrowings have been eliminated following the early settlement of the Nedbank term loan and the repayment of a loan by the Zimbabwean operation.
The Group is in a net cash position of R156 million, following the acquisition of Genop and is comfortably able to service its obligations in the short-term with a working capital facility of R850 million and a term facility of R250 million, the latter available until December 2018.