


Over the counter
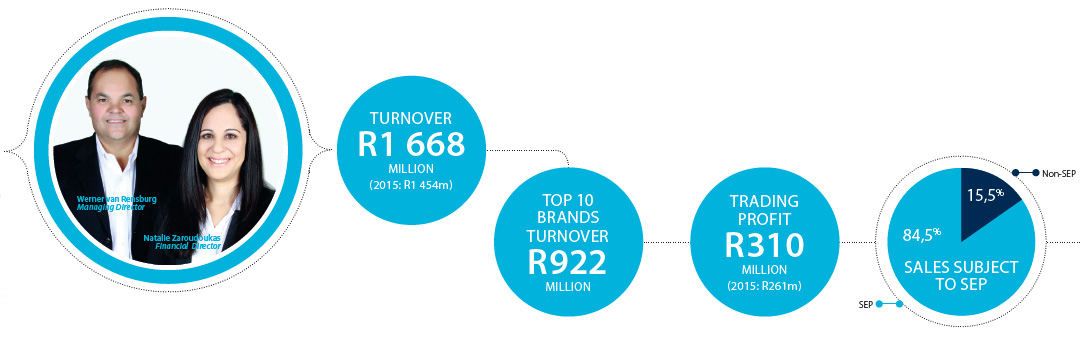
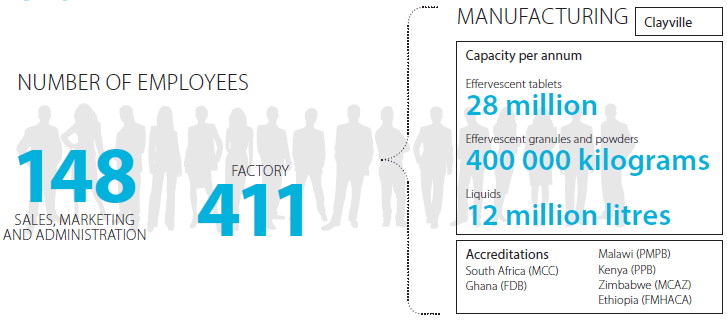
Over the Counter (OTC) supplies medication for patients in South Africa’s private and public sectors, competing in the self-medication Pharmacy and FMCG sectors of the market with a complement of 88 premium and economy brands.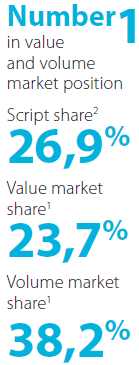 |
 |
1 IMS MAT June 2016
2 Impact Rx June 2016
OVERVIEW
The OTC division has improved its volume and value market leadership position in the private market, growing 5% ahead of the market at 10%.
Two in every five packs of Schedule 1 and Schedule 2 products, sold in the private sector, is an Adcock Ingram product.
The business competes in the following core categories within the market:
Pain  |
Cough and Cold |
Allergy | Heartburn and Indigestion |
Energy |
||||||||||
 |
The pain portfolio is the market leader in pharmacy with a 38,8% volume share and 43,9% value share. Adco-dol is the top ranked analgesic brand in pharmacy. In the Schedule 2 muscle relaxant market Spasmend is ranked number 2 in value and volume. | In this mature market, the portfolio continues to grow ahead of the market, maintaining and stretching its leadership position in Pharmacy. Adcock Ingram brands have strong representation across all indications including antitussives, expectorants, decongestants and analgesic combinations. The cold and flu portfolio has a 29,7% value share and a 43% volume share in Pharmacy. | Allergex is the market leader in the systemic oral antihistamine market with more than 50% volume share, and showing double digit value growth of 12,5%. With the launch of Ceticit and Adco-Desloratadine in 2015 and Levogex in April 2016, the business is now represented in 80% of the anti-histamine market with first, second and third generation offerings. | Citro-Soda is the top ranked urinary alkaliniser in both pharmacy and FMCG and has built trust for its extended indications viz. indigestion, heartburn and gout. The division also has a very strong portfolio of anti-diarrhoeal products including brands such as Adco-Loperamide, Adco-Prodium, Betaperamide and Pectrolyte. Mayogel has recently been listed in the FMCG channel. It is the largest brand by volume in this market in Pharmacy. | Vita-Thion and Liviton are well respected energy brands, both ranked in the top 5 brands sold in pharmacy. Vita-Thion has a particularly attractive positioning with its unique sustainable energy proposition. | |||||||||
 |
||||||||||||||
| TOP TEN BRANDS | MARKET TRENDS | STRATEGIC FOCUS | ||||||||||||||||||||||||||||||||||||||||||||||
|
|
|