



 39 / 182

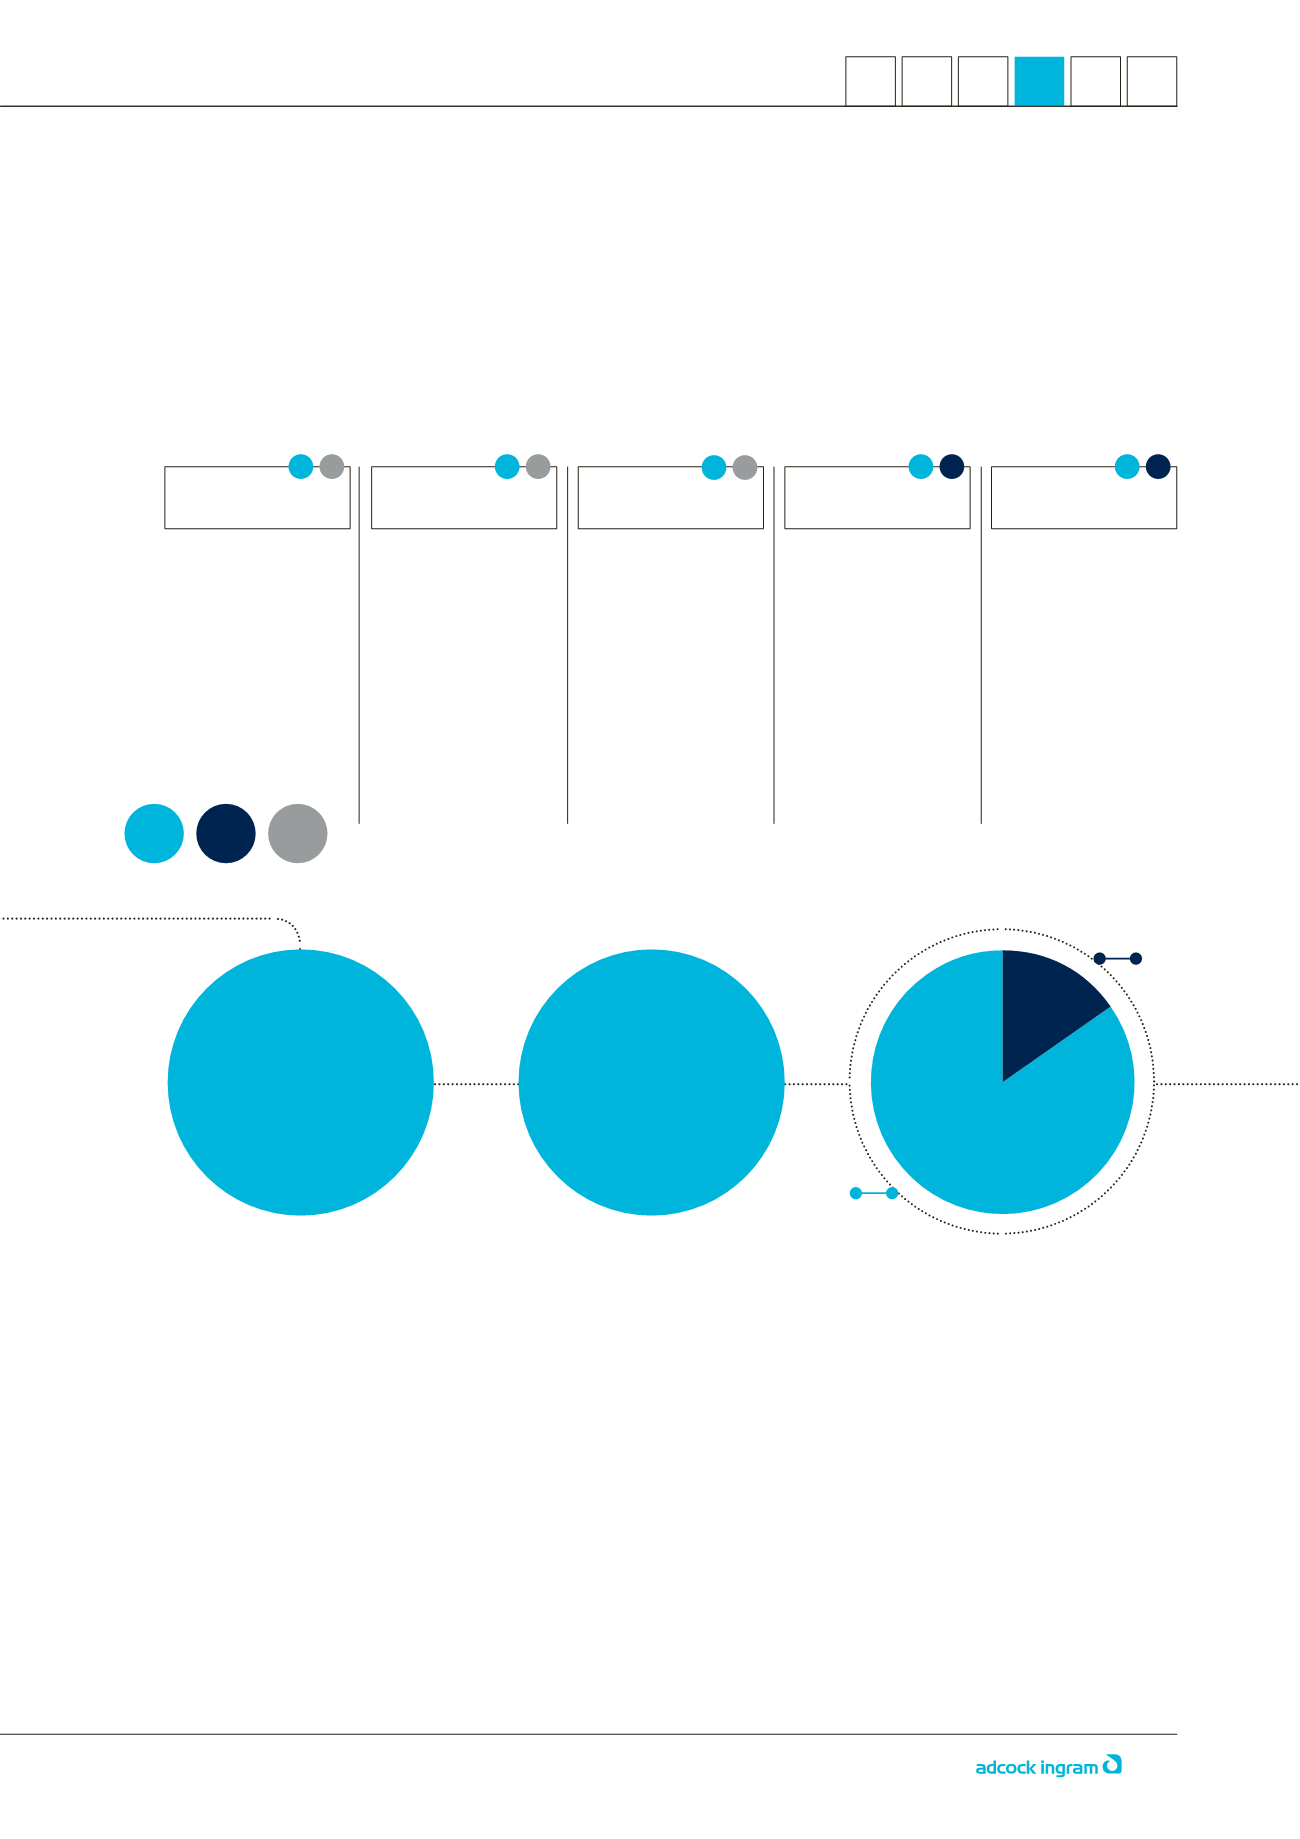
•
Protect and build heritage brands
•
Develop and expand categories and channels
•
Ensure compliance in a changing regulatory
environment
•
Launch innovative products
•
Add value to customers through excellence in
service delivery
•
Gain further consumer, shopper and customer
insight to support marketing plans
•
Increase production and improve efficiencies in
the manufacturing plant and laboratory
STRATEGIC FOCUS
MARKET TRENDS
TOP TEN BRANDS
•
Growth in the OTC market is being driven by
the trend towards wellness, self-care and patient
education
•
Innovation remains an important growth driver in
terms of diagnosis, methods of curative care and
on the preventative side
•
Economic factors continue to cause a shift from
premium brands to economy brands and smaller
pack sizes
•
Consumers are showing a bias towards
convenience, specifically in the channels they
select (i.e. one stop shop for all requirements)
as well as in the growth of convenient dosage
formats (i.e. sachets)
•
Retailer loyalty programs are driving consumer
behaviour and consumption
•
Adco-Dol
•
Corenza C
•
Allergex
•
BronCleer
•
Citro-Soda
•
Alcophyllex
•
Betapyn
•
Dilinct
•
Napamol
•
Solphyllex
SALES SUBJECT
TO SEP
Non-SEP
15,5
%
84,5
%
TOP 10
BRANDS
TURNOVER
R922
MILLION
TRADING
PROFIT
R310
MILLION
(2015: R261m)
SEP
OVERVIEW
The OTC division has improved its volume and value market leadership position in the private market, growing 5% ahead of the market at 10%.
Two in every five packs of Schedule 1 and Schedule 2 products, sold in the private sector, is an Adcock Ingram product.
The business competes in the following core categories within the market:
Pharmacy
rank
FMCG
rank
Script
share
rank
Pain
#
1
#
1
The pain portfolio is the mar-
ket leader in pharmacy with a
38,8% volume share and 43,9%
value share. Adco-dol is the
top ranked analgesic brand in
pharmacy. In the Schedule 2
muscle relaxantmarketSpasmend
is ranked number 2 in value
and volume.
Cough and Cold
#
1
#
1
In this mature market, the
portfolio continues to grow
ahead of the market, main-
taining and stretching its
leadership position in Phar-
macy. Adcock Ingram brands
have strong representation
across all indications includ-
ing antitussives, expectorants,
decongestants and analgesic
combinations. The cold and
flu portfolio has a 29,7% value
share and a 43% volume share
in Pharmacy.
Allergy
#
1
#
1
Allergex
is
the
market
leader in the systemic oral
antihistamine market with
more than 50% volume share,
and showing double digit
value growth of 12,5%. With
the launch of Ceticit and
Adco-Desloratadine in 2015
and Levogex in April 2016, the
business is now represented
in 80% of the anti-histamine
market with first, second and
third generation offerings.
Heartburn and
Indigestion
#
3
#
2
Citro-Soda is the top ranked
urinary alkaliniser in both phar-
macy and FMCG and has built
trust for its extended indications
viz. indigestion, heartburn and
gout. The division also has a very
strong portfolio of anti-diarrhoeal
products
including
brands
such
as
Adco-Loperamide,
Adco-Prodium,
Betaperamide
and Pectrolyte. Mayogel has
recently been listed in the FMCG
channel. It is the largest brand
by volume in this market in
Pharmacy.
Energy
#
3
#
2
Vita-Thion and Liviton are well
respected energy brands, both
ranked in the top 5 brands
sold in pharmacy. Vita-Thion
has a particularly attractive po-
sitioning with its unique sus-
tainable energy proposition.
PERFORMANCE
FIVE
SIX
THREE
ONE
FOUR
TWO
OUR PERFORMANCE
(continued)
| 35
Integrated Report 2016